Home News
14-Oct-2026 06:43 PM
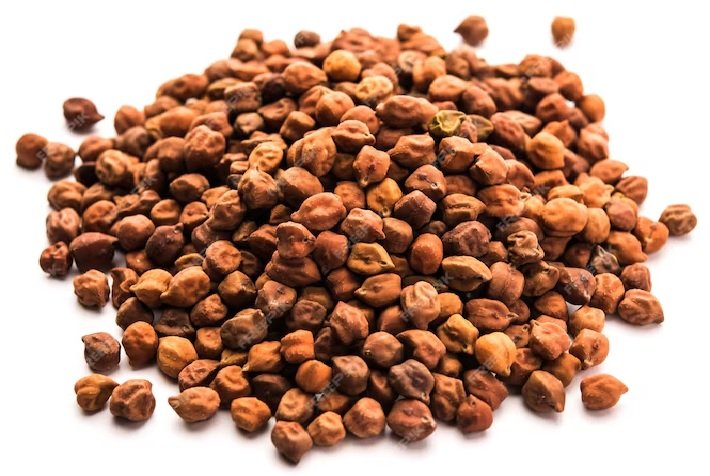
Domestic chana prices are trending downwards due to weak demand from pulse mills, increased profit-booking by stockists, and speculation regarding the removal of import duties on the commodity. However, the decline is being somewhat contained as selling pressure at higher price levels remains limited.
In Delhi, chana prices fell by ₹100 per quintal today due to subdued buying interest. Following this drop, prices for the Madhya Pradesh variety settled at ₹7,375–7,400 per quintal, while the Rajasthan variety stood at ₹7,450 per quintal. Similar softening in prices was observed in other major producing markets.
In Indore, chana prices fell by ₹100 to ₹7,500–7,650 per quintal, and in Katni, they dropped by ₹150 to ₹7,400–7,450 per quintal. Prices in Akola declined by ₹125 to ₹7,700–7,750 per quintal, while Nagpur saw a ₹100 drop, settling at ₹7,700–7,750 per quintal.
The decline and weak demand for domestic chana also impacted imported varieties. In Mumbai, Tanzanian chana softened by ₹100–150 to ₹7,350–7,400 per quintal, and Australian chana stood at ₹7,500–7,550 per quintal. At the Mundra and Kandla ports, Australian chana was quoted at ₹7,375–7,400 per quintal.
Supply-side factors may provide support despite weak demand
Demand for *chana dal* (split gram) and *besan* (gram flour) is expected to rise due to the upcoming consumption season; however, buying by pulse mills currently remains sluggish. Mills hold limited stocks of *chana* (gram) in the domestic market, and arrivals of indigenous *chana* at producing *mandis* (wholesale markets) are falling short of requirements.
Stocks of imported *chana* at ports are reportedly limited. With reduced imports from Tanzania and high costs associated with sourcing from Australia, the availability and cost of imported stock remain critical factors for the domestic market.
Meanwhile, concerns persist regarding *chana* sowing for the upcoming *Rabi* season due to depleted soil moisture in key producing states. Crop prospects are also being closely monitored following the declaration of drought conditions in several areas of Karnataka and Maharashtra.
Market Outlook
Currently, the *chana* market is under pressure due to weak demand, profit-booking by stockists, and speculation regarding the removal of import duties. However, limited domestic availability, high import costs, and uncertainty surrounding the upcoming *Rabi* sowing could provide support to prices.